No products in the cart.
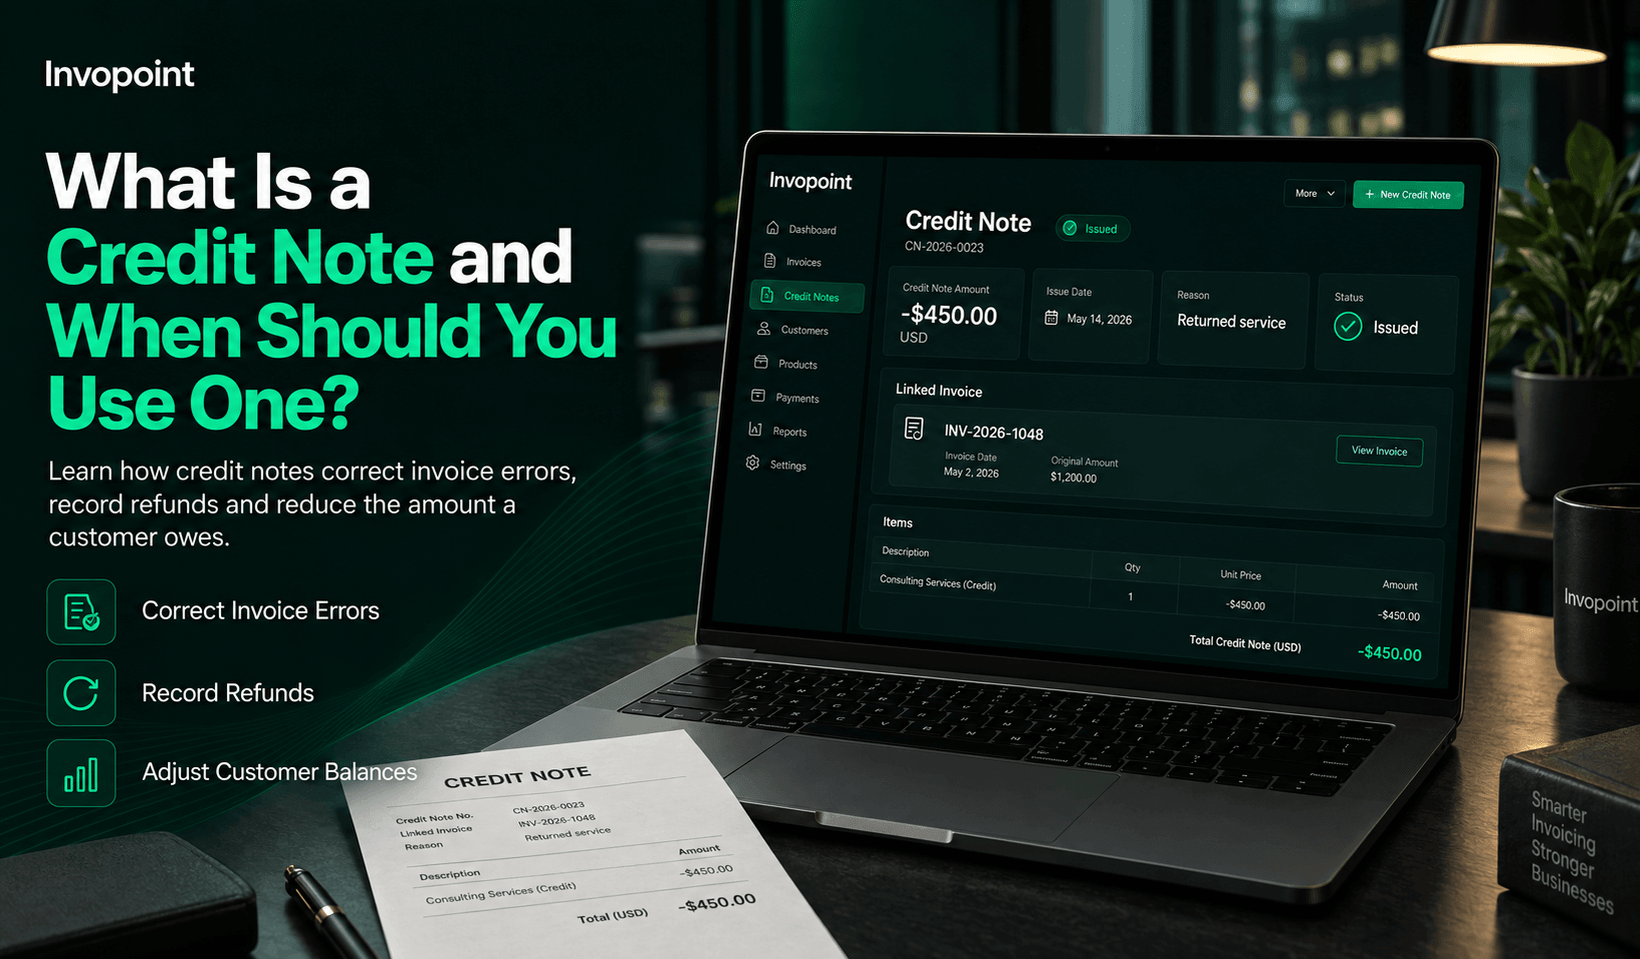
A credit note and when should you use one explained with practical steps, common mistakes, examples, FAQs, and relevant Invopoint tools for small businesses, finance teams, and B2B service providers.
A reliable approach to credit note and when should you use one combines commercial clarity, accurate data, visible responsibility, and timely follow-up. Software can support those controls, but it cannot replace a decision about how the workflow should operate.
An invoice is a commercial document that records what a seller supplied, what the customer owes, when payment is due, and how payment should be made. This guide explains the operating choices, controls, measures, and common errors relevant to credit note and when should you use one.
Contract, tax, payment, and record-retention requirements vary by jurisdiction. Treat this article as operational guidance and confirm material legal or tax decisions locally.
In practical terms, the business should confirm the legal business and customer details, describe the supplied work in language the buyer can verify, and calculate subtotal, discounts, tax, and the final balance. It should then assign a unique invoice number and an unambiguous due date and send the invoice through a traceable channel and retain the record. This sequence supports the main objective: issue clear, professional invoices that clients can approve and pay with less friction.
For credit note and when should you use one, the operational answer should be specific enough that two team members would reach the same result from the same information. Ambiguous guidance creates hidden exceptions and inconsistent customer treatment.
Incomplete or inconsistent invoices create avoidable questions, corrections, and payment delays. The cost is not limited to administrative time. It can affect customer trust, working capital, reporting accuracy, and the team’s ability to forecast what happens next.
The strongest approach treats credit note and when should you use one as part of the invoice-to-cash system. Sales terms, delivery evidence, customer master data, billing, payment, and reconciliation should agree. When one stage uses different information, the exception usually appears later as a correction, dispute, or overdue balance.
For management, the objective is issue clear, professional invoices that clients can approve and pay with less friction. That requires a process owner, a consistent routine, and a small number of measures that reveal whether the workflow is improving.
Choose measures that expose delay, error, risk, cash impact, or profitability. Define each metric once, keep its source consistent, and pair it with an action owner.
Track the trend and investigate the largest exceptions rather than relying only on an average. A metric becomes useful only when someone can act on the process behind the result.
Define the calculation, source, owner, and review frequency so the result remains comparable. A metric becomes useful only when someone can act on the process behind the result.
Segment the result by customer, service, team, or period to reveal the operational cause. A metric becomes useful only when someone can act on the process behind the result.
Connect the measure to a decision, threshold, and named action owner. A metric becomes useful only when someone can act on the process behind the result.
Use the Payment Processing Fee Calculator to turn part of this topic into a practical calculation or document. The free tool provides an immediate result and a transparent starting point for the next business decision.
For a wider workflow, Online Invoicing Software connects invoice creation, client records, payment tracking, recurring billing, and reporting. The article explains the decision, the tool supports the calculation, and the product page shows how the process can be managed over time.
Browse the complete collection at 100 free business calculators. Each tool provides an immediate calculation that can support pricing, billing, tax, cash-flow, or operating decisions.
These supporting articles cover adjacent search questions without repeating the same primary search intent.
An invoice is a commercial document that records what a seller supplied, what the customer owes, when payment is due, and how payment should be made. In practice, the exact implementation should reflect the contract, customer process, and jurisdiction.
Incomplete or inconsistent invoices create avoidable questions, corrections, and payment delays. A controlled approach helps the business issue clear, professional invoices that clients can approve and pay with less friction.
Start with confirm the legal business and customer details, then describe the supplied work in language the buyer can verify. This exposes missing information before the invoice or decision reaches the customer.
Invopoint helps B2B businesses create professional invoices, maintain client records, track paid and overdue balances, support online payments, and review billing activity in one workspace.
Reporting should separate timing problems from accuracy problems. An invoice can be correct but late, or timely but incomplete, and each failure requires a different operational response. Review the workflow from the customer perspective as well as the internal perspective. A process that is efficient for the seller may still delay payment if the buyer cannot match the invoice to an approved purchase or delivery record.
Document reason codes for corrections, rejections, disputes, and delayed payments. A short controlled list makes recurring causes visible and supports a focused improvement plan instead of anecdotal debate. The team should reconcile statuses with financial reality. Sent, viewed, approved, paid, partially paid, disputed, written off, and cancelled must have precise meanings and should not be inferred from an email thread.
For cross-border work, confirm currency, tax treatment, legal entity, customer location, payment route, and record-retention requirements before the first invoice. Retrofitting these decisions later can create avoidable corrections. Changes should be introduced with an owner, effective date, documented rationale, and success measure. Without these elements, the business cannot tell whether results changed because of the new process or normal variation.
Training should use real scenarios and role-specific instructions. A billing administrator, sales lead, delivery manager, and finance reviewer need different details even when they participate in the same end-to-end process. Access should follow responsibility. Users need enough permission to complete their role, while approvals, sensitive changes, refunds, write-offs, and configuration updates should remain restricted and reviewable.
Month-end review should not be the first time the business notices an issue. Weekly visibility into exceptions, overdue balances, rejected records, and incomplete customer information allows smaller corrective actions. Calculate the cost of the current process using time, corrections, delayed cash, payment fees, and write-offs. This creates a credible baseline for evaluating whether a new workflow or system produces measurable value.
Keep the implementation connected to issue clear, professional invoices that clients can approve and pay with less friction. Features are relevant only when they reduce a known constraint, improve a decision, strengthen control, or make the customer payment journey easier. A quarterly review should examine policy exceptions, customer behavior, metric trends, and user feedback together. Operational data explains what happened, while interviews often reveal why the result occurred.
If teams operate across the USA, UK, and Europe, maintain a common global workflow with controlled local variations. Separate processes for every market create unnecessary complexity unless regulation or customer practice genuinely requires them. Internal links, templates, calculators, and software should support the same decision path. Educational content explains the issue, a calculator tests assumptions, and the operational platform records the resulting invoice and payment status.
The best approach to credit note and when should you use one is a documented workflow that people can follow and management can measure. Start with the commercial trigger, required data, customer approval route, and exception owner. Add automation where the rule is stable enough to automate.
Invopoint helps businesses create professional invoices, maintain client records, support online payments, track paid and overdue balances, and review billing activity. Start with the online invoice generator or explore the free business calculators for the next practical step.
 Anton Liashenko
Apr 17, 2024
 Anton Liashenko
Apr 24, 2024
 Anton Liashenko
Nov 17, 2023
 Anton Liashenko
Nov 13, 2023
 Anton Liashenko
Nov 08, 2023